May 12th, 2009 · Comments Off on Is the Philadelphia Real Estate Market Recovering?
As long as I have been in the real estate business, I have been told that real estate is an economic leader. We are first in and we are first out. A cliche that has been true in every recession I have experienced.
You’ll remember that residential real estate was the first part of the economy to feel the changes from the boom to our current economic readjustment. Economic indicators were pointing to issues in the market just before we began experiencing the effects of those issues. The good news (for those of us who own homes or invest in real estate) is that we seem to be seeing some signs indicating that may be the next step in the process.
In a recent article in Realty Times, Kenneth R. Harney pointed out the following positive economic indicators;
Pending home sales took a 3.2 percent jump last month — the second straight month of positive growth. These are signed home sale contracts that haven’t yet gone to closing, but are scheduled to do so in the next 60 to 90 days.
Lawrence Yun, chief economist for the National Association of Realtors, said we’re now at “the leading edge of first time buyers responding to very favorable affordability conditions, and an $8,000 tax credit.”
Mortgage applications for future home purchases also surged again, up five percent nationwide last month, according to the Mortgage Bankers Association. Rates are firming up in response to the rising demand for mortgage money. They rose last week on average to 4.8 percent for 30 year fixed rate loans and 4.6 percent for 15 year mortgages.
In a market like Philadelphia, where our average prices have seen little readjustment from their historically affordable levels, these indicators may indeed herald the long awaited “bottom” of the residential real estate market. Fueled by basic human needs rather than rampant speculation, our market has remained stable, with only single digit price adjustments inthe past 2 years, and some makret areas actually seeing increases in price even in this environment.
So if you have been thinking of “making your move” in the real estate market, now may just be the moment you’ve been waiting for. As I have mentioned in earlier posts, buying real estate for a longer term financial benefit has always been a good thing to d, since time will ease any market adjustments in your favor. With these indicators, that logic is reinforced by the immediate benefots of the current market. So i f you have a reason to buy, and have been waiting for the right time, your wait may well be over.
Tags: Economy · Local · New Jersey · Pennsylvania · Real Estate
May 1st, 2009 · Comments Off on How Swine Flu Helps Mortgage Rates
 Monday, mortgage markets improved with news of new Swine Flu cases.
It’s a classic example of Safe Haven buying and today’s rate shoppers will see the benefits.
Mortgage rates improved about 0.125 percent Monday.
It’s not an official term, but “Safe Haven buying” describes the trading patterns in which large numbers of investors move money away from risky investments and toward safer ones. As a general rule in Safe Haven buying, stocks sell off and bonds make gains, including mortgage-backed bonds.
Fears that a global Swine Flu outbreak would slow the global recovery is a major reason why mortgage rates improved Monday.
Dumping risk is a common reaction on Wall Street when unexpected events occur. Because the future is uncertain, traders prefer to play it safe. Hence the jargon-like term, “Safe Haven buying”.
If nothing else, Monday’s mortgage rate action reminds us that the biggest influences on the market are often not the events we can prepare for. It’s the events we never saw coming.
This morning, with known Swine Flu cases spreading to Asia and a Phase 4 Alert from the World Health Organization, Safe Haven buying is continuing. However, with the Federal Reserve meeting today and tomorrow, markets could be ripe for a correction.
(Image courtesy: Niman and Google Maps)
Tags: Economy · Mortgage Lending · Real Estate
April 30th, 2009 · Comments Off on Examining The Federal Reserve in Plain English

The Federal Open Market Committee voted to leave the Fed Funds Rate unchanged today within its target range of 0.000-0.250 percent. The Fed also reiterated its plan to support the mortgage market to the tune of $1.5 trillion.
In its press release, the FOMC noted that the economy may still be contracting, but that it’s not happening with the same speed as in prior months. Household spending is stabilizing and financial markets are “easing”.
Nevertheless, threats to the recovery are everywhere with the following items on the Fed’s short list:
- The growing ranks of unemployed workers
- The reduction of housing wealth nationally
- Reduced inventories and investment from business
Furthermore, the FOMC fingered today’s inflation levels as too low to support economic growth. This justifies the Fed’s plan to hold the Fed Funds Rate near zero percent “for an extended period”.
For home buyers and refinancing homeowners, today’s press release was not favorable.
After the Fed’s announcement, stock markets rallied on the idea that the worst of the economy really is over and that led to a broad bond market sell-off. Mortgage rates spiked in response, adding as much as 0.125 percent, in some cases.
The FOMC’s next scheduled meeting is June 23-24, 2009.
Source
Parsing the Fed Statement
The Wall Street Journal Online
April 29, 2009
http://online.wsj.com/public/resources/documents/info-fedparse0904.html
Tags: Economy · Federal Reserve · Real Estate
April 28th, 2009 · Comments Off on The Real Deal About SUSHI!
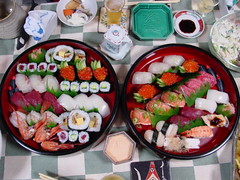
Image by apc33 via Flickr
The kitchen in our homes is statistically the most “lived in” room for most of us. So what better reason is there to enjoy the many pleasures that come from preparing authentic international dishes that are as good or better than those you get at a restaurant for you, your family, and friends.
Back in 1983, when there were only about two Japanese Sushi restaurants in the Philadelphia area I became as fascinated with learning how to make this “magical” food as I was with making doves appear from silk scarves. So, when not performing magic shows or helping people sell and buy real estate, my kitchen became my stage and it was fish that I was cutting in half instead of my human assistants. I bought the books, took the classes, and frequented the hard to find(at the time)Asian supermarkets to insure that my home-made sushi was “restaurant perfect”. Unfortunately, these days, the many “fusion” restaurants that serve sushi do not make this delicacy in the true Japanese style.
Hundreds of years ago, before the days of refrigeration, fishermen in Japan would lay beds of rice down on planks by the seashore. The rice was mixed with a brine of sugar, vinegar, and salt and basically was “pickled” so that the fish that was layed on it would cure to preserve it. The rice would be discarded and not eaten. Many years later this custom changed when someone decided to taste the rice along with the fish.
The real deal about sushi is that it does not mean “raw fish”. Raw fish is called Sashimi. By definition sushi means…pickled rice. So what we are eating in all of the non Japanese buffets and the like is technically not true Japanese sushi, but instead, a dissapointing facsimile of the food I fell in love with many years ago. It doesn’t matter if you use corned beef, raw fish, grilled chicken breast, or vegetables either on top or rolled into sushi rice with or without nori seaweed. For sushi to be sushi you must use pickled rice. And here’s how to make it…
3 1/3 cups-short grain Japanese rice(not Chinese long grain rice and not Japanese “sweet or glutinous rice”)
4 cups-water
1-4 inch square-Konbu(Japanese dried seaweed, optional, lightly scored)
5 tblsp.-unseasoned Japanese rice vinegar
5 tblsp.-sugar
4 tsp.-salt
Lay Konbu on top of rice and water in pot. When they come to a boil over medium-high heat, close the lid and reduce heat to verrrrry low for 20 minutes. Then shut off heat, remove pot from stove, and let rice finish steaming with lid on for another 20 minutes. Discard Konbu and transfer rice into a large wooden bowl and sprinkle with the pickling solution of vinegar, sugar, and salt while tossing with a wooden paddle and force cooling with a small electric fan mounted above the bowl(the sushi chefs of old would have their apprentices fan the rice manually as part of their training). It is very important to cool the rice quickly. Transfer the rice to a smaller bowl and cover with plastic wrap. Note: pickled sushi rice only stays fresh for one day and does not lend itself to any other recipes like fried rice, soups, etc. Now that you have the RIGHT recipe for sushi rice, continue making your favorite sushi dish from a host of recipes you can find in your local book store or the internet. Enjoy your sushi, enjoy your kitchen, and enjoy your HOME!

Tags: Consumer Interest · Just For Fun
April 24th, 2009 · Comments Off on 7 Gadgets To Consider On Mother’s Day Or Father Day’s
After attending the International Home and Housewares show, The Today Show filmed a 5-minute segment called “Housewares You Won’t Be Able To Live Without”.
The title is somewhat over-the-top but don’t let that turn you off. The gadgets reviewed are both practical and inexpensive. They include:
- Make-no-mess vegetable peeler
 for the kitchen
- Efficient kabob tool
 for the grill
- Grow-In-Your-Kitchen garden
 that grows like an outdoor one
Of over 2,000 products at the show, NBC selected seven. Watch the video to see them in action.
Gadgets don’t improve a home’s value but they can make life easier sometimes. And for homeowners, easier is often better.
Tags: Consumer Interest · Just For Fun · Real Estate
April 23rd, 2009 · Comments Off on 50% of the Country’s Foreclosures Are in Three States
 Since 2007, foreclosures have dominated real estate news. You can’t turn on the news or open a paper without some foreclosure-related story.
But for all of the discussion, foreclosures continue to be geographically concentrated.
Adding up the latest stats from RealtyTrac.com , more than half of the country’s foreclosure actions from March occurred in just 3 states — California, Florida and Nevada.
Those 3 states represent just 19 percent of the nation’s population.
Despite the local concentration of foreclosures, however, they remain a national problem. This is because mortgage lenders lend in all 50 states — not just 3 of them — so the impact of mortgage defaults in one region can quickly spread to others.
In part because of foreclosures are higher, the following has happened:
- Mortgage guidelines have tightened
- Downpayment requirements have increased
- Private mortgage insurance has become more expensive
That’s an important set of changes for a would-be borrower. In some cases, it can keep a person from qualifying.
Search the March 2009 foreclosure report for yourself on RealtyTrac.com’s website.
Tags: Economy · Mortgage Lending · Real Estate
April 22nd, 2009 · Comments Off on Loan Modification Part 6 – Finalizing your loan modification
Congratulations! Your loan modification is almost done. Here are just a few tips to wrap up the process.
You’ll receive a loan modification packet from your bank that looks very similar to loan documents. Review them to ensure the following terms are what you agreed to:
- Interest rate
- Interest rate reset cap
- Term of modification (how many years)
- Monthly payment
- Good faith payment due
- New principal balance of your loan
If all of these are in good shape you’ll need to:
- Sign the documents in the presence of a notary
- File a copy for yourself
- Wire good faith payment funds to the bank via the wiring instructions they provide (they will not accept a personal check)
Once that’s all done your loan modification is complete. Congratulations! You made it.
Stay tuned to this blog for more great real estate, mortgage and loan modification advice. Thanks for reading and please share this series with friends and family who may need this help.
Tags: Consumer Lending · Economy · Mortgage Lending
April 21st, 2009 · Comments Off on Loan Modification Part 5 Negotiating new loan terms
If you’ve gotten this far, congratulations! It means you’ve been approved as a loan modification candidate and the bank has or will be making you an offer very soon. This post will cover some ways to negotiate with your lender to get the best possible modified terms for your new mortgage.
What to expect from your bank offer
If the bank does approve you for a home loan modification there are a few constants that you must be aware of:
- The bank will not write down the principal balance of your loan, they will adjust your interest rate to lower your payments, but you’ll still owe the same amount on your mortgage.
- The bank will not waive late payments. These will usually be added to your principal and tacked on the back of the loan.
- The bank will require a good faith payment ranging from one to two month’s mortgage payment as a sign of good faith that you’re committed to the mortgage.
- The bank will demand that you have the ability to afford a reasonable market interest rate as part of your modification. (You won’t be negotiating for 1% when the going rate for a 30-year fixed is 6.25%.)
What you can negotiate
- Interest rate. Your interest rate will typically be reduced between 2% and 4%. If you’re interest rate is currently 9% after an ARM adjustment, you can negotiate for a 6% 30-year loan fixed for 5-years no problem. You will have problems negotiating for a 3%. It’s not going to happen.
- Post-modification adjustment cap. After a fixed period (typically 5 years) your modification will expire and your rate will become adjustable again. You can negotiate the cap of your adjustment. Say if you agree to a 6% loan you can negotiate a cap at 8% or something similar to protect you from a similar reset disaster in the future.
- Good faith payment. Every bank will require a good faith payment of some sort to get caught up with delinquent payments before they go through with a loan modification. This is typically one to two months of mortgage payments. If you’re in a bind this may not be feasible. You can often negotiate this down to half a mortgage payment. Either way you’ll need to make some sort of payment – be prepared for that.
Take yourself out of the equation emotionally
Your home is an emotional asset. Your family lives there, it holds your memories, etc. Do not let you emotions get in the way of negotiating. Use these tips to be a better negotiator with the bank:
- Have a game plan. Have a hoped-for mortgage payment and interest rate so that you know what you’re negotiating for. Stick to your guns and be firm on the terms so you can get the best deal possible.
- Keep a calm demeanor and realize you’re working with another human who can either help you or make your life hell. Work to make them want to help you more.
- Be polite, yet assertive. If you don’t agree with something speak up and voice your objection. Be polite, but know what you want and stick to your guns.
- Appeal to people’s sense of fairness. Use terms like “doesn’t that seem fair?” or “isn’t that reasonable?” People have a hard time objecting to something that seems fair or reasonable.
- Get something if you’re asked to give something. Quid pro quo is fine here. If you’re asked to give something up (like a slightly higher monthly payment) then ask for something in return – a lower good faith payment, for example.
- Document everything. Don’t get stuck in a game of he said, she said. Write down offers so that you have a record of what’s on the table at any given time.
- Elevate to a decision-maker. Feel free to ask to speak to a manager or supervisor if you’re dissatisfied with your progress.
Negotiate to a point where you’re in the target range of your hoped for mortgage payment and interest rate and good faith payment. Once you’re there take the offer. No need to get greedy when your home is on the line. Next we’ll talk about wrapping up your loan modification.
Tags: Consumer Lending · Economy · Mortgage Lending
April 20th, 2009 · Comments Off on Loan Modification Part 4 -Tips for qualifying!
So far we’ve discussed the basics as it relates to getting a loan modification. Now we’ll talk about a few tips that will help you qualify for a loan modification. These tips are centered around your hardship letter and the monthly expense worksheet.
The hardship letter
Called an LOE in the biz (letter of explanation) this letter is your explanation of why you believe you qualify for a home loan modification. Remember these facts when writing your hardship letter:
Banks want to work with people that:
- Are credit-worthy and have a good payment history
- Have been in their home for a long time
- That have been impacted by an unusual adverse event
- Have good potential to keep earning their current level of income
- Have good potential to pay back the mortgage
- Are likely not to go in to default after modification
Banks don’t want to work with people that:
- Have been chronically late in making mortgage payments
- Have lived in their home less than a year
- Are a poor credit risk
- Have lost their primary source of income
- Are likely to go in to default after modification
You want to write your hardship letter with these facts in mind. A good hardship letter includes:
- An explanation of the event that caused you to fall behind on your mortgage (or if you’re current why you’re requesting a modification). This should be positioned honestly as a one-time setback that is in the past.
- These can range from your adjustable rate mortgage resetting, to an illness now recovered, to a job loss that has been replaced by a new, stable and similar paying position. These are all one-time events that don’t impact your ability to pay a reduced amount moving forward.
- A statement of your desire to stay in the home and make paying the mortgage a priority.
- A statement of why your situation was temporary and one-time.
- A statement of why your situation is improving.
If you’d like a free hardship letter simply subscribe to Blown Mortgage’s Loan Modification Tips email list.
Be brief and to the point. We don’t need a novel, just a straightforward and accurate letter that states your willingness to stay in the home and the freak nature of the event that caused you to request a loan modification.
Monthly expense worksheet
Because your DTI is such a critical part of calculating whether you qualify or not, we want to be as high-level in our detail reporting to the bank. This means that we want to focus on big ticket items that we know will be consistent month-to-month and not the variable expenses that we can control through sacrifice and restraint.
Recommendations for your expense worksheet:
- Submit your own first. Let the lender ask for more detail. Your expense worksheet should include all items on your credit report and nothing else. Car, home, credit cards, student loans or second mortgages are the big ones.
- Variable expenses should be left off initially since it is impossible to predict the future and how your spending will change – it all comes down to the modification before you can accurately calculate that expense.
- If you are close to 50% call your credit card companies and ask for a reduction in your monthly payments. Even if you can save $40 per month on each card you could benefit with a lower DTI.
- Can you live without HBO? If you’re on the border look for ways to shave dollars off monthly expenses. While these won’t be in round one of our expense report it’s important to keep these in our back pocket for possible reductions.
- Double-check your expenses. Are you self-employed and pay for your car from your business? That doesn’t go on your expenses as it’s a business expense.
By preparing your own financial worksheet first you can save the time of filling out the lender’s which is often more detailed and time consuming and present your application quickly to the lender. If the processor accepts your application as is you’ve gained valuable time. If they request one of their own then you’ll have the information already collected. However; by preparing a detailed and accurate monthly expense worksheet that focuses on the items on your credit report and grouped in high-level buckets you’ll make it easy for the bank to see your financial snapshot and determine whether you’re a good candidate for modification.
With all the demand for modifications, making the bank’s life easy goes a long way. Remember these are just people swamped with work and in a demanding job where they have to say “no” a lot. Give them a reason to enjoy working on your file by being organized, efficient and together and you’ll get better treatment than someone who is difficult, disorganized and non-responsive. In the next post we’ll discuss negotiating your modification terms.
Tags: Consumer Lending · Economy · Mortgage Lending
April 16th, 2009 · Comments Off on Loan Modification Part 4 Tips for qualifying
So far we’ve discussed the basics as it relates to getting a loan modification. Now we’ll talk about a few tips that will help you qualify for a loan modification. These tips are centered around your hardship letter and the monthly expense worksheet.
The hardship letter
Called an LOE in the biz (letter of explanation) this letter is your explanation of why you believe you qualify for a home loan modification. Remember these facts when writing your hardship letter:
Banks want to work with people that:
- Are credit-worthy and have a good payment history
- Have been in their home for a long time
- That have been impacted by an unusual adverse event
- Have good potential to keep earning their current level of income
- Have good potential to pay back the mortgage
- Are likely not to go in to default after modification
Banks don’t want to work with people that:
- Have been chronically late in making mortgage payments
- Have lived in their home less than a year
- Are a poor credit risk
- Have lost their primary source of income
- Are likely to go in to default after modification
You want to write your hardship letter with these facts in mind. A good hardship letter includes:
- An explanation of the event that caused you to fall behind on your mortgage (or if you’re current why you’re requesting a modification). This should be positioned honestly as a one-time setback that is in the past.
- These can range from your adjustable rate mortgage resetting, to an illness now recovered, to a job loss that has been replaced by a new, stable and similar paying position. These are all one-time events that don’t impact your ability to pay a reduced amount moving forward.
- A statement of your desire to stay in the home and make paying the mortgage a priority.
- A statement of why your situation was temporary and one-time.
- A statement of why your situation is improving.
If you’d like a free hardship letter simply subscribe to Blown Mortgage’s Loan Modification Tips email list.
Be brief and to the point. We don’t need a novel, just a straightforward and accurate letter that states your willingness to stay in the home and the freak nature of the event that caused you to request a loan modification.
Monthly expense worksheet
Because your DTI is such a critical part of calculating whether you qualify or not, we want to be as high-level in our detail reporting to the bank. This means that we want to focus on big ticket items that we know will be consistent month-to-month and not the variable expenses that we can control through sacrifice and restraint.
Recommendations for your expense worksheet:
- Submit your own first. Let the lender ask for more detail. Your expense worksheet should include all items on your credit report and nothing else. Car, home, credit cards, student loans or second mortgages are the big ones.
- Variable expenses should be left off initially since it is impossible to predict the future and how your spending will change – it all comes down to the modification before you can accurately calculate that expense.
- If you are close to 50% call your credit card companies and ask for a reduction in your monthly payments. Even if you can save $40 per month on each card you could benefit with a lower DTI.
- Can you live without HBO? If you’re on the border look for ways to shave dollars off monthly expenses. While these won’t be in round one of our expense report it’s important to keep these in our back pocket for possible reductions.
- Double-check your expenses. Are you self-employed and pay for your car from your business? That doesn’t go on your expenses as it’s a business expense.
By preparing your own financial worksheet first you can save the time of filling out the lender’s which is often more detailed and time consuming and present your application quickly to the lender. If the processor accepts your application as is you’ve gained valuable time. If they request one of their own then you’ll have the information already collected. However; by preparing a detailed and accurate monthly expense worksheet that focuses on the items on your credit report and grouped in high-level buckets you’ll make it easy for the bank to see your financial snapshot and determine whether you’re a good candidate for modification.
With all the demand for modifications, making the bank’s life easy goes a long way. Remember these are just people swamped with work and in a demanding job where they have to say “no” a lot. Give them a reason to enjoy working on your file by being organized, efficient and together and you’ll get better treatment than someone who is difficult, disorganized and non-responsive. In the next post we’ll discuss negotiating your modification terms.
Tags: Consumer Lending · Economy · Mortgage Lending